
Largest Surge Of 115.8% QoQ In Residential Sector, Followed By A 16.7% Qoq Expansion In Commercial Sector
Savills Research shares that real estate investment sales rose 52.6% quarter-on-quarter (QoQ) to S$6.48 billion in the second quarter of 2024. Mainly driven by higher proceeds from the sale of state land under the GLS Programme, S$3.16 billion was awarded for the four residential sites and one industrial site, more than double the value from the previous quarter. (See Table 1)
The proceeds were from the plots at:
• Zion Road (Parcel A) – won by a joint venture between City Developments Limited (CDL) and Mitsui Fudosan for nearly S$1.11 billion or a land rate of S$1,202 per sq ft per plot ratio (psf ppr) in April.
• Upper Thomson Road (Parcel B) – awarded to GuocoLand and Hong Leong Holdings unit, Intrepid Investments, for S$779.6 million or S$905 psf ppr in the same month.
• Holland Drive site – sold to CapitaLand and a UOL-led consortium with the winning bid of S$805.4 million or S$1,285 psf ppr in May.
• River Valley Green (Parcel A) – won by Wing Tai Holdings for S$464 million, translating to S$1,325 psf ppr in June.
The private sector saw an increase of 14% QoQ in transaction value to S$3.32 billion in Q2/2024. In terms of transaction volume, the quarterly growth was higher by 30.8%, rising from 65 deals in Q1 to 85 in Q2. This is mainly attributed to the residential property sector with 52 luxury homes (each priced S$10 million and above) sold in Q2, up from 40 a quarter ago – suggesting some recovery in the luxury housing market.
Transaction volume in other property sectors such as commercial and industrial, remained relatively stable compared with the previous quarter. Due to higher financing costs and delays in Fed rate cuts, divestment of non-core assets to reduce leverage and support growth by vendors, including S-REITs and listed developers, continued on the commercial and industrial property front.
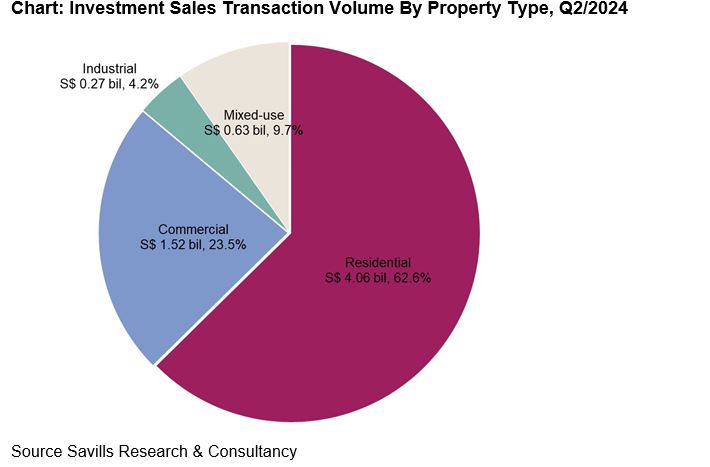
Commercial investment sales expanded by 16.7% QoQ to S$1.52 billion in Q2/2024, making up 23.5% of the quarter’s total transaction value. The largest deal sealed was Mapletree Pan Asia Commercial Trust (MPACT)’s S$775 million divestment of Mapletree Anson, a 19-storey office building located on Anson Road in Tanjong Pagar. This translates to a price of S$2,352 psf based on a net lettable area of 329,487 sq ft and represents a gain of S$10 million over the property’s valuation in March this year. (See Table 2)
Q2 investment sales in the mixed-use property sector totalled S$628.9 million, contributing 9.7% of the total transaction value. These came from the sales of three properties: Delfi Orchard, Fraser Residence River Promenade and Sin Ming Centre. The biggest deal was the collective sale of Delfi Orchard by CDL for S$439 million.
Jeremy Lake, Managing Director, Investment Sales & Capital Markets at Savills Singapore says, “More properties have been launched for sale in the last 6 months with some sellers deciding to adopt proactive sale strategies rather than sitting passively and waiting for buyers to come along. While the appetite from buyers has improved, there is still a price gap in many cases and only some of the properties will be sold.”
Alan Cheong, Executive Director, Research & Consultancy, Savills Singapore adds, “Presently, the market expects at least one rate cut for 2024. Although this may just be a symbolic 25 basis points reduction, the mood is now one that anticipates that rates have peaked. Therefore, any cut would help lift sentiments. We maintain our forecast of S$22 to S$23 billion in total investment sales for 2024, up from S$19.7 billion recorded last year.”
Click here to view table 1: Top Land Sales in the Public Sector, Q2/2024
Click here to view table 2: Top Private Investment Sales, Q2/2024
Click here to view chart:Investment Sales Transaction Volume By Property Type, Q2/2024
Click here to read Singapore Sales and Investment Q2 Briefing 2024